How Much Does Workers’ Comp Insurance Cost for Tree Service Companies in California?
See How We're Different
or call us: 866-226-4436
How Much Does Workers’ Comp Insurance Cost for Tree Service Companies in California?
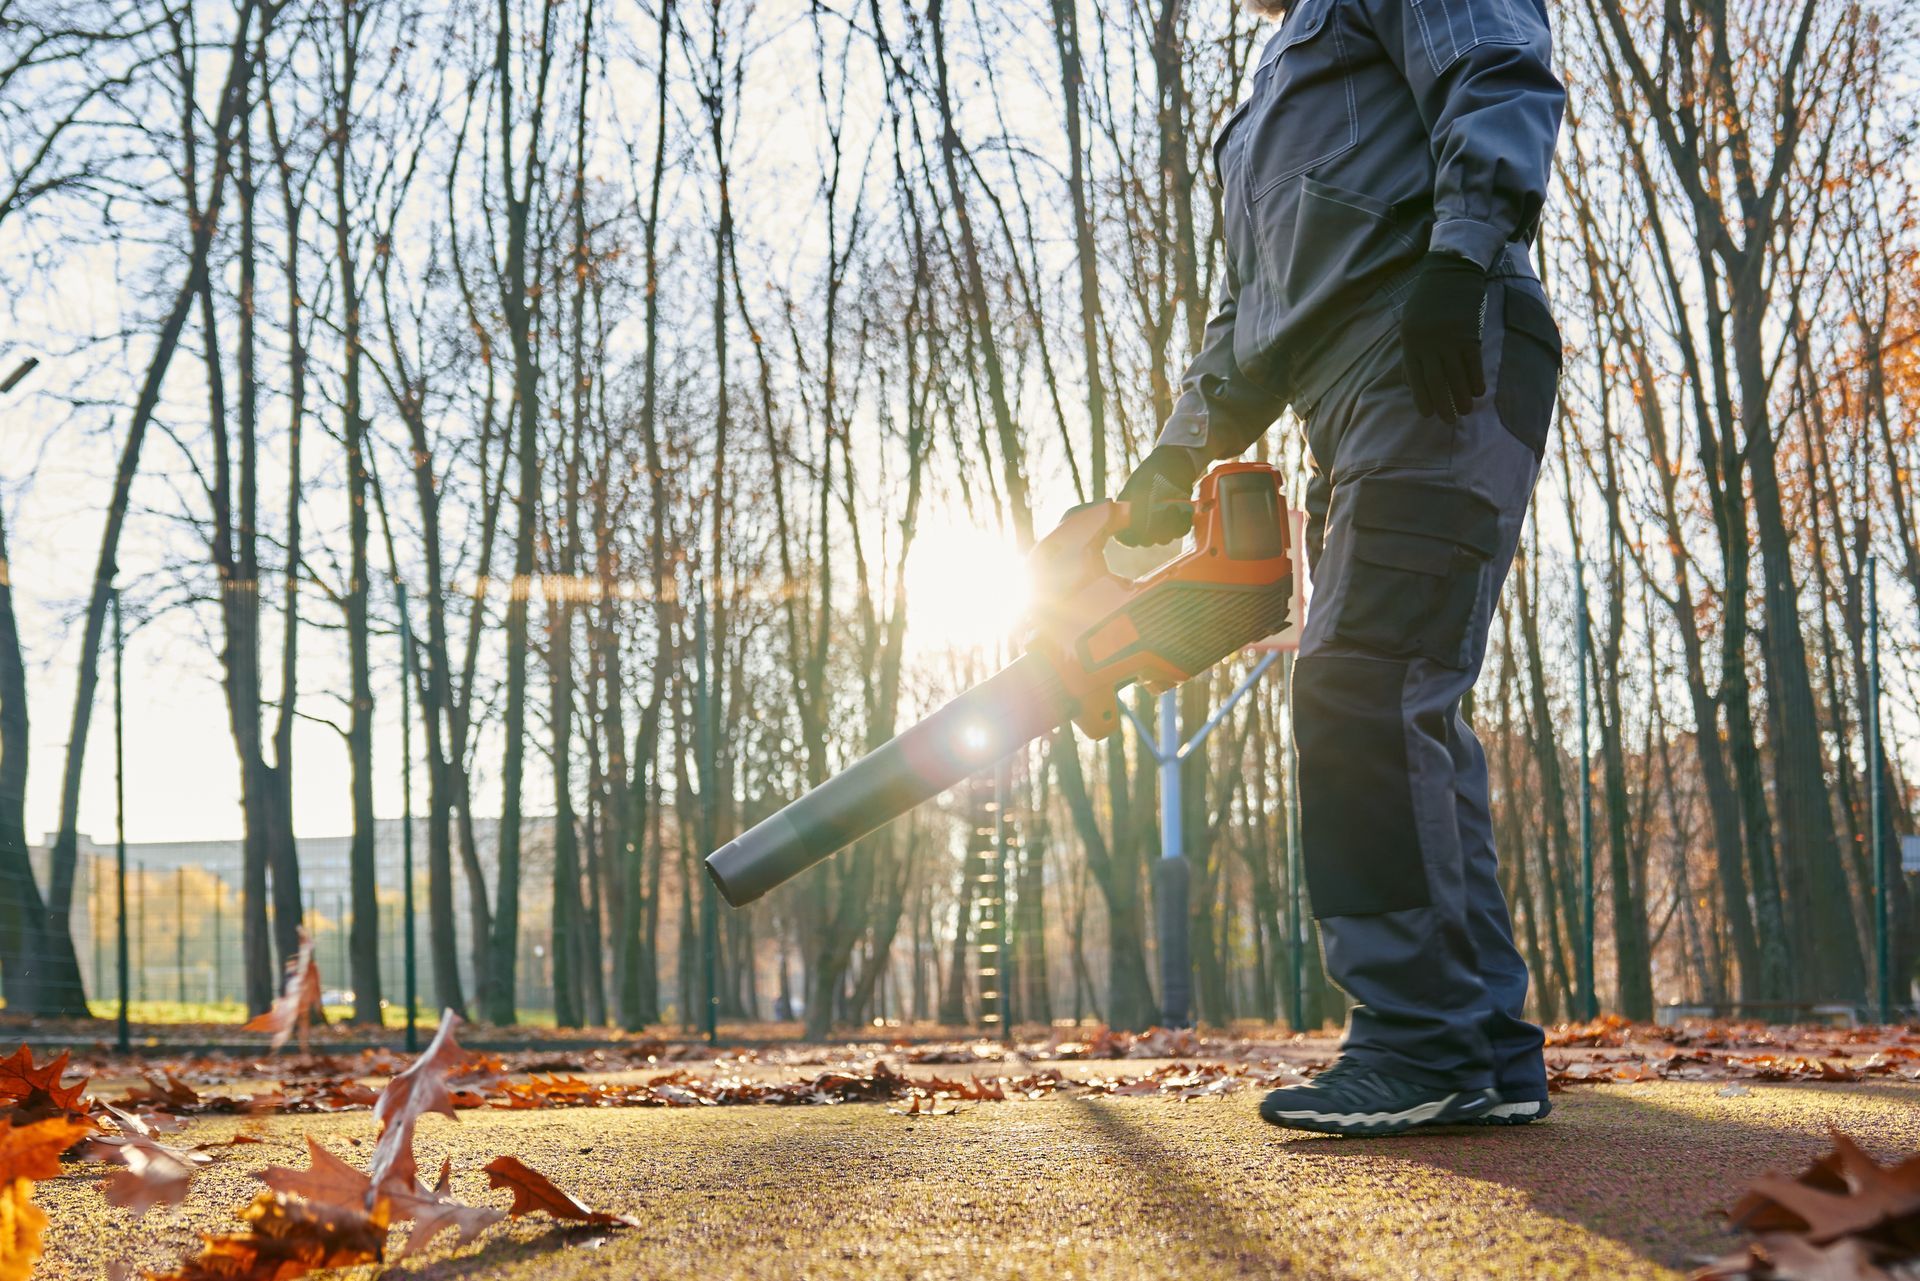
Workers’ compensation insurance is an essential expense for tree service companies operating in California. Whether a business specializes in tree trimming, tree removal, stump grinding, or emergency storm cleanup, its employees often work in hazardous conditions. Climbing tall trees, operating chainsaws, handling heavy branches, and working near power lines can expose workers to serious injuries. Workers’ compensation insurance helps businesses manage the financial consequences of workplace accidents while providing benefits to eligible employees.
The cost of workers’ compensation insurance for tree service companies in California varies depending on several factors, including payroll, job duties, employee classifications, claims history, and the company’s overall safety practices. Understanding these factors can help business owners estimate their insurance expenses and identify opportunities to control costs.
What Is the Average Cost of Workers’ Comp Insurance for Tree Service Companies in California?
There is no single price that applies to every tree service business in California. Tree care operations generally face greater workplace risks than many office-based or low-hazard businesses, which can result in higher workers’ compensation premiums.
Insurance costs are often calculated using a rate per $100 of payroll for each employee classification. The applicable rate depends on the insurer, the classification assigned to the work, the company’s experience, and other underwriting considerations. Because tree removal and climbing involve substantial physical risks, a business performing these services may pay considerably more than a company primarily offering ground-level landscaping or administrative services.
For example, a tree service company with a small crew and modest annual payroll will generally have different insurance expenses from a larger operation employing multiple climbers, equipment operators, and ground workers. Business owners should request a customized quote rather than relying on a general industry average that may not reflect their specific operations.
Key Factors That Influence Workers’ Compensation Premiums
Employee Payroll and Workforce Size
Payroll is one of the most important elements in determining workers’ compensation costs. As a company’s payroll increases, its premium will generally increase as well, assuming the same classification rates and other rating factors. A business employing several full-time tree climbers may have higher insurance costs than a smaller company with limited staffing.
California insurers typically evaluate payroll according to the applicable classification rules. Accurate payroll records are therefore important when obtaining a quote, managing the policy, and completing an end-of-term premium audit.
Type of Tree Service Work Performed
The specific services offered by a company can significantly affect its insurance costs. Tree removal, aerial climbing, large-branch cutting, and emergency work may present different levels of risk from routine maintenance performed at ground level.
Insurers consider the actual duties employees perform when determining appropriate classifications. Companies should clearly explain whether their workers climb trees, operate bucket trucks, use chainsaws, remove large trunks, or perform other specialized tasks. Providing accurate information helps reduce the likelihood of classification disputes and unexpected premium adjustments.
Claims History and Workplace Safety
A company’s previous workers’ compensation claims can influence its future insurance costs. Frequent claims or expensive workplace injuries may affect its experience modification factor when the business qualifies for experience rating.
Employers can help reduce preventable accidents by training employees, maintaining equipment, using appropriate protective gear, establishing safe climbing procedures, and documenting workplace safety practices. Although these measures cannot eliminate every accident, a consistent safety program can help reduce injuries and demonstrate responsible risk management.
Employee Classification and Job Responsibilities
Not every employee in a tree service company performs the same work. Climbers, ground crew members, drivers, equipment operators, and office staff may have different classification requirements under applicable workers’ compensation rating rules.
The correct classification depends on the actual work performed and the governing rules, not simply the employee’s job title. Separating eligible payroll by classification and maintaining accurate records can help ensure the premium calculation reflects the company’s operations.
How Workers’ Compensation Insurance Is Calculated
Workers’ compensation premiums are commonly calculated by multiplying the applicable classification rate by the covered payroll, expressed in units of $100. Insurers may then apply an experience modification factor and other permitted rating adjustments, subject to the policy’s rating rules.
For instance, imagine a tree service company has $300,000 in annual payroll assigned to a hypothetical classification rate of $25 per $100 of payroll. The preliminary calculation would be $75,000 before applicable experience modifications, other adjustments, minimum premiums, and any relevant charges or credits. This example is purely illustrative and does not represent a current California market rate or a quote for a particular business.
The final premium may differ because insurers evaluate the company’s individual risk profile and apply their approved rating methods. An accurate estimate requires current classification rates, verified payroll information, and details about the work performed.
Recent News