Workers’ Comp Insurance in California: A Complete Guide for Commercial Builders
See How We're Different
or call us: 866-226-4436
Workers’ Comp Insurance in California: A Complete Guide for Commercial Builders
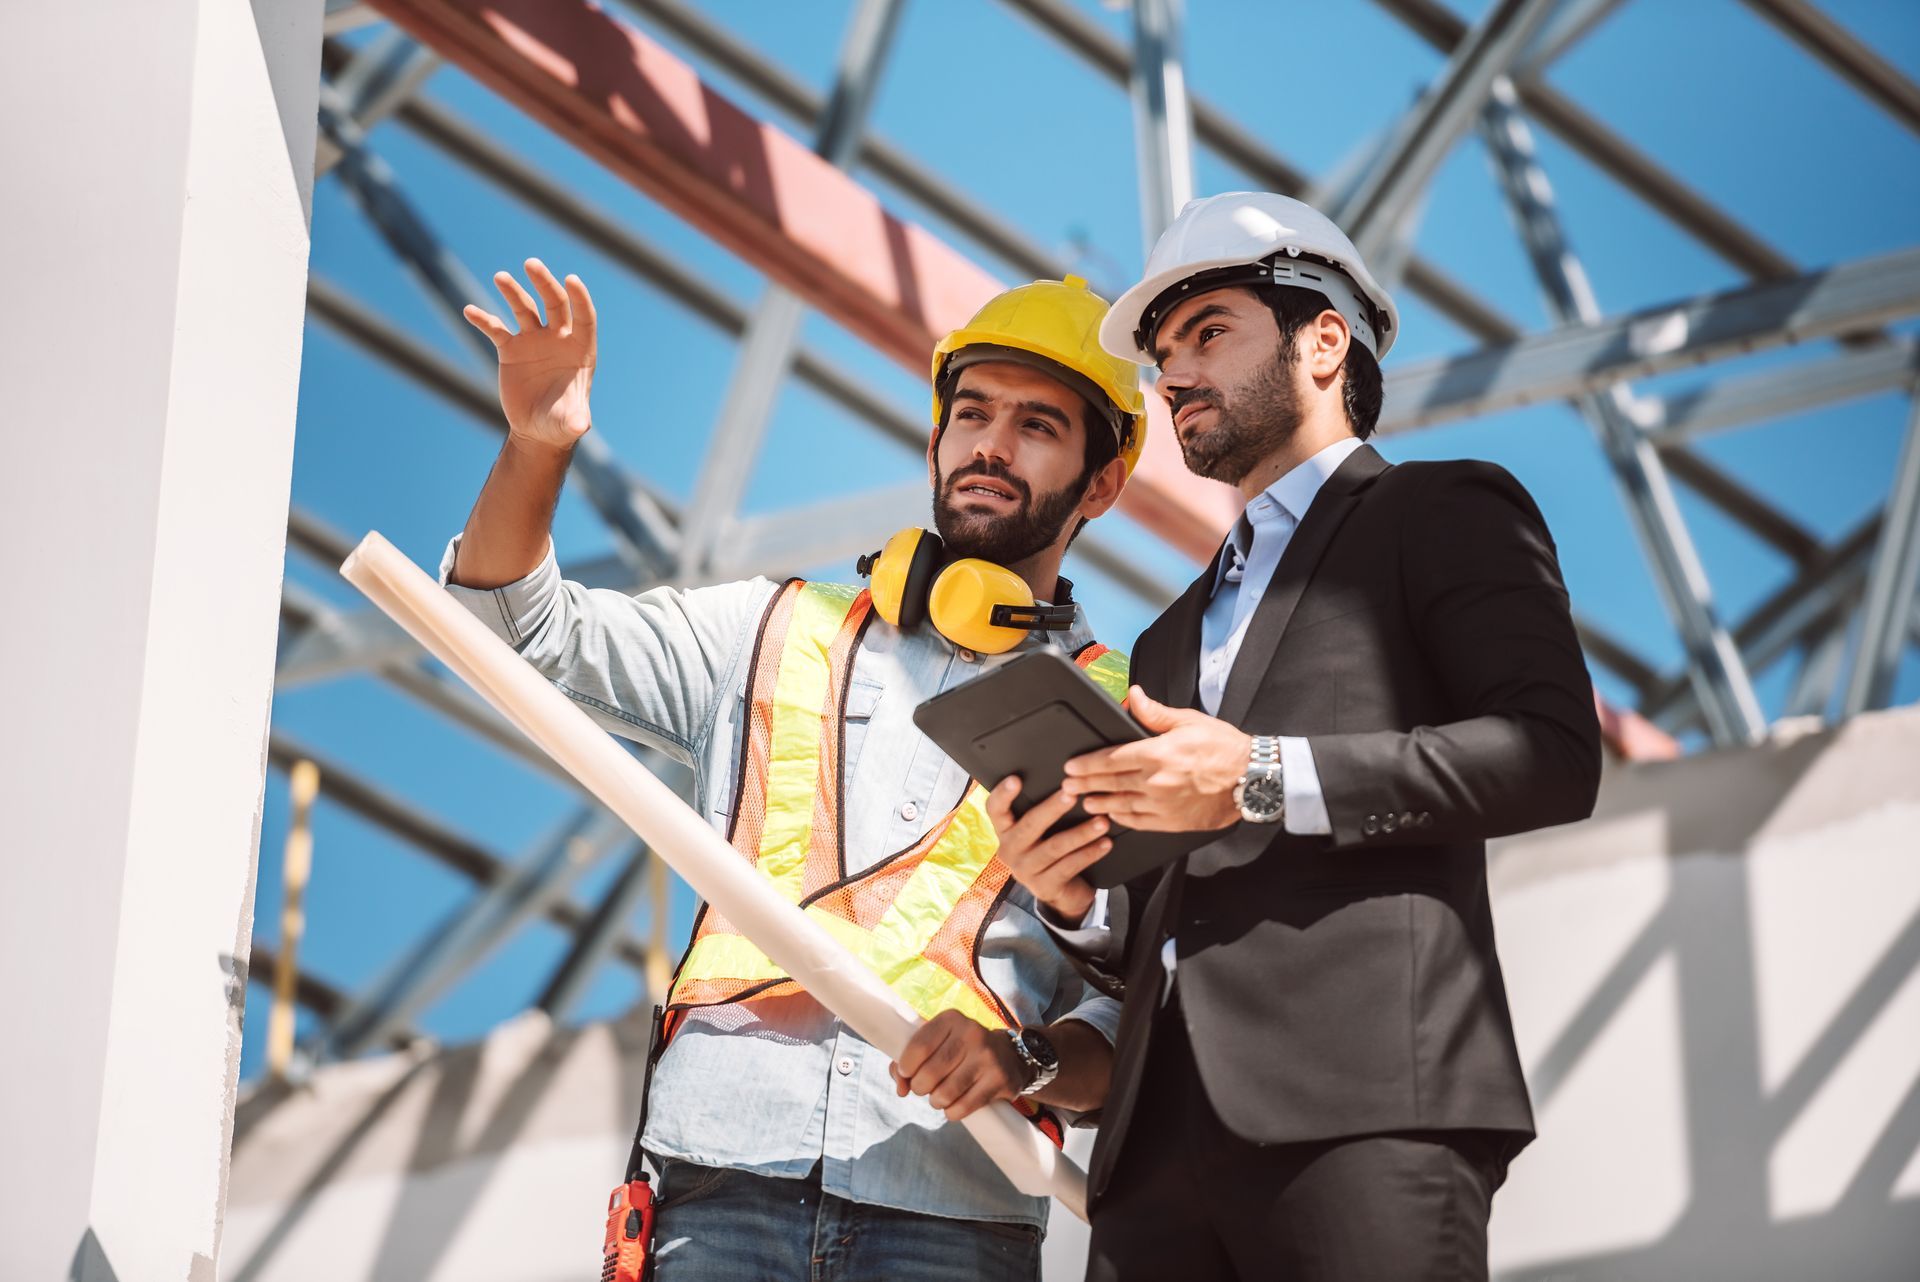
Commercial construction is one of the most demanding industries in California, involving heavy equipment, complex building projects, tight deadlines, and employees working in potentially hazardous environments. From office buildings and retail centers to warehouses and industrial facilities, commercial builders must manage numerous risks while maintaining workplace safety and meeting project requirements. One of the most important ways to protect a construction business and its workforce is through workers’ compensation insurance.
Workers’ compensation insurance helps provide financial and medical support when employees experience work-related injuries or illnesses. For California commercial builders, understanding how this coverage works is essential for protecting employees, managing business expenses, and complying with state regulations. This guide explains the importance of workers’ compensation insurance, its major benefits, coverage considerations, costs, and practical steps builders can take to choose appropriate protection.
Understanding Workers’ Compensation Insurance in California
Workers’ compensation insurance is designed to help employees recover from injuries or illnesses connected to their employment. In California, employers generally must carry workers’ compensation insurance even if they employ only one worker. Specific exemptions and rules may apply to certain business structures and employment arrangements, so construction companies should confirm their obligations under current state law.
For commercial builders, this coverage is particularly important because construction work can involve falls from elevated surfaces, injuries caused by power tools, equipment accidents, exposure to hazardous materials, and repetitive physical strain. Even with proper safety procedures, workplace incidents can happen unexpectedly.
Workers’ compensation generally covers reasonable and necessary medical treatment, temporary disability benefits when an employee cannot work during recovery, permanent disability benefits when an injury causes lasting impairment, and supplemental job displacement benefits when eligible workers cannot return to their previous employment. Eligible dependents may also receive death benefits following a fatal work-related incident.
The precise benefits depend on California law, the circumstances of the claim, and the employee’s medical condition.
Why Commercial Builders Need Workers’ Compensation Coverage
Commercial construction projects often involve multiple trades, subcontractors, specialized machinery, and constantly changing work environments. These conditions make workplace injuries a significant concern for contractors of every size.
Without appropriate insurance, a builder may face substantial financial pressure from medical expenses, employee disability benefits, regulatory penalties, and disruptions to project schedules. Failure to maintain legally required coverage can also expose a business to serious enforcement consequences and potential work stoppages.
Workers’ compensation insurance helps eligible employees access benefits without having to rely entirely on personal resources after a workplace injury. It also provides employers with an established process for handling covered claims and may limit certain employee lawsuits under California’s workers’ compensation system, subject to important legal exceptions.
For commercial builders pursuing large contracts, maintaining appropriate coverage can also demonstrate professionalism and support compliance with general contractor, project owner, and construction management requirements.
What Does Workers’ Compensation Insurance Cover?
Workers’ compensation policies are intended to address qualifying occupational injuries and illnesses rather than ordinary health conditions unrelated to employment. For example, a construction worker who fractures a leg after falling at a job site may qualify for medical treatment and disability benefits. Similarly, an employee who develops a qualifying occupational illness because of workplace exposure may be eligible for benefits.
Coverage can include emergency treatment, doctor visits, hospital services, prescribed medications, rehabilitation, and other medically necessary care permitted under applicable rules. Wage-replacement benefits may help workers manage lost income when an injury prevents them from performing their regular duties.
Commercial builders should understand that workers’ compensation is not a substitute for general liability insurance, commercial auto insurance, or builders risk coverage. Each policy addresses different exposures. General liability insurance, for instance, commonly addresses certain third-party bodily injury and property damage claims, while workers’ compensation focuses on eligible employee injuries and occupational illnesses.
Understanding these distinctions helps contractors build a more complete insurance program.
How Much Does Workers’ Compensation Insurance Cost?
The cost of workers’ compensation insurance in California varies according to several factors, including the type of construction work performed, payroll size, employee job classifications, claims history, and the insurer’s pricing approach. High-risk construction activities generally have different insurance costs from lower-risk administrative work.
A commercial builder employing roofers, concrete workers, steel installers, and equipment operators may pay a different premium from a company primarily coordinating projects through office-based staff. Insurers use job classifications to assess the relative risks associated with different duties.
Payroll is another important consideration because premiums are commonly calculated using payroll amounts and applicable classification rates, with adjustments that may apply. A business’s prior claims and experience modification factor, when applicable, can also influence its final premium.
Builders can manage costs by maintaining accurate payroll records, classifying employees correctly, implementing effective safety programs, reporting injuries promptly, and reviewing their policies regularly. Comparing quotations from qualified insurers or brokers can also help contractors evaluate available coverage and pricing.
The lowest quotation is not always the best choice. Builders should review policy terms, insurer service, claims support, and the suitability of coverage before making a decision.
Choosing the Right Workers’ Compensation Policy
Selecting appropriate workers’ compensation insurance requires commercial builders to evaluate their workforce, projects, and contractual responsibilities. Contractors should provide accurate information about their operations, including the types of construction activities they perform, the number of employees they have, and their estimated annual payroll.
It is also important to examine how subcontractors are handled. In California, subcontractor insurance status can affect a contractor’s exposure, and certain workers may be treated as employees under applicable law despite the wording of a contract. Builders should verify certificates of insurance and confirm that subcontractors maintain appropriate coverage rather than assuming that every independent contractor arrangement eliminates responsibility.
Before purchasing a policy, contractors should understand how claims are reported, which classifications apply to their workforce, how payroll adjustments are handled, and what documentation is needed during an audit. Reviewing these details with a knowledgeable insurance professional can help prevent avoidable disputes and unexpected premium adjustments.
Workplace Safety and Risk Management
Insurance is only one part of a strong construction risk management strategy. Commercial builders should also create practical workplace safety procedures that address the hazards associated with each project.
Regular safety training, appropriate personal protective equipment, equipment inspections, fall-prevention systems, and clear communication between supervisors and workers can help reduce preventable accidents. Contractors should also establish procedures for documenting incidents and ensuring that injured employees receive prompt medical attention.
A well-organized safety program can support employee well-being, reduce operational interruptions, and potentially improve insurance performance over time. Builders should review their procedures as projects change and ensure that workers understand the safety expectations relevant to their specific tasks.
Recent News