Workers’ Compensation Insurance for General Contractors in California: What You Need to Know
See How We're Different
or call us: 866-226-4436
Workers’ Compensation Insurance for General Contractors in California: What You Need to Know
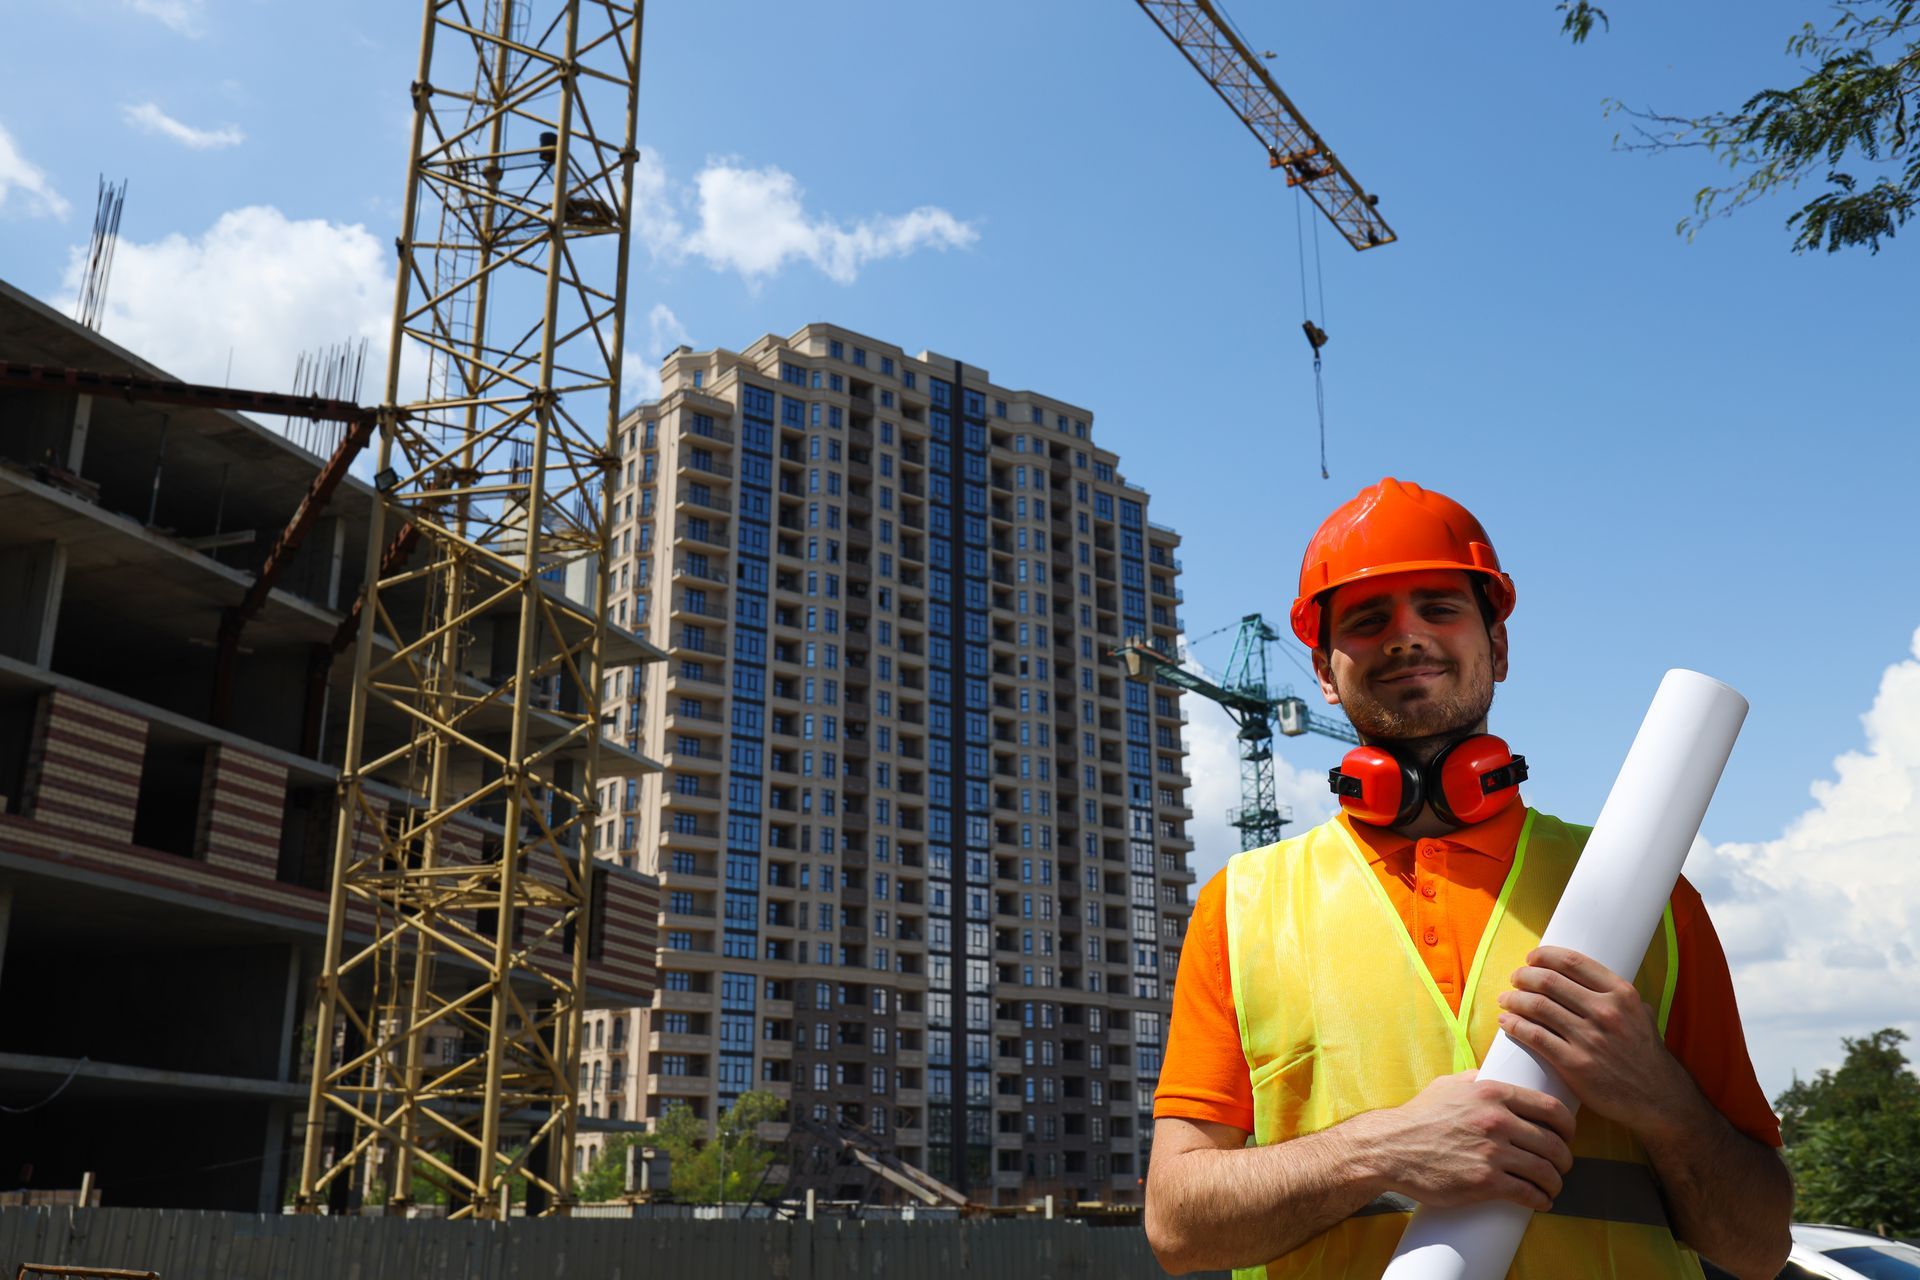
General contractors in California work in a demanding industry where workplace safety, project deadlines, and financial responsibilities must be managed carefully. From residential renovations to large commercial construction projects, contractors face potential risks every day. Employees may suffer injuries while operating heavy machinery, working at heights, handling construction materials, or performing physically demanding tasks. Workers’ compensation insurance helps protect injured employees while providing important financial and legal protection for qualifying employers.
For general contractors, understanding California’s workers’ compensation requirements is essential to maintaining compliance, protecting workers, and keeping construction projects running smoothly. Whether you operate a small contracting business or oversee multiple construction sites, choosing appropriate coverage can make a significant difference in your business’s long-term stability.
Understanding Workers’ Compensation Insurance in California
Workers’ compensation insurance is designed to provide benefits to employees who experience work-related injuries or illnesses. Depending on the circumstances, these benefits may cover medical treatment, a portion of lost wages, temporary or permanent disability benefits, and other payments allowed under California law.
Unlike ordinary health insurance, workers’ compensation specifically addresses qualifying workplace injuries and occupational illnesses. For construction businesses, this distinction is particularly important because job-site hazards can lead to costly medical expenses, extended recovery periods, and disruptions to scheduled work.
California generally requires employers to carry workers’ compensation insurance when they have employees, even if they employ only one person. Certain rules and exceptions may apply depending on the business structure and the individuals involved. General contractors should therefore review their employment arrangements carefully instead of assuming that a small workforce eliminates their insurance obligations.
Why General Contractors Need Proper Coverage
Construction projects involve multiple trades, specialized equipment, and constantly changing work environments. A general contractor may coordinate carpenters, electricians, plumbers, roofers, laborers, and other professionals throughout a single project. Each activity introduces different workplace risks that require appropriate planning and supervision.
Workers’ compensation coverage helps ensure that eligible employees can access benefits following covered work-related injuries. It also helps businesses manage expenses that could otherwise place considerable pressure on their finances.
Without required insurance, a contractor may face serious consequences, including state enforcement actions, financial penalties, project interruptions, and potential liability for workplace injury costs. In California, failing to secure mandatory workers’ compensation coverage can also result in criminal penalties under applicable law.
Maintaining suitable insurance demonstrates a commitment to worker welfare and responsible business management. It may also help strengthen professional relationships with property owners, developers, construction managers, and other parties that require evidence of insurance before allowing work to begin.
California’s Requirements for Employees and Subcontractors
One of the most important responsibilities for general contractors is determining which workers require coverage. California generally requires employers to provide workers’ compensation insurance for their employees, regardless of whether they work full-time, part-time, or temporarily.
Subcontractor arrangements can make compliance more complicated. A contractor cannot automatically assume that every person described as an independent contractor is legally self-employed. California applies specific legal tests to determine employment status, and the actual working relationship may matter more than the label used in a contract.
General contractors should obtain and review current workers’ compensation certificates from subcontractors who have employees. They should also verify that the coverage remains active throughout the project. If a subcontractor lacks required insurance or is incorrectly classified, the general contractor may face additional exposure depending on the circumstances and applicable law.
Careful documentation, written agreements, and regular insurance verification can reduce uncertainty. Contractors should consult a qualified insurance professional or California employment attorney when ownership structures, independent contractors, or subcontractor classifications create questions about coverage obligations.
Factors That Influence Workers’ Compensation Costs
The cost of workers’ compensation insurance varies from one construction business to another. Insurers generally consider factors such as the type of construction work performed, employee payroll, job classifications, claims history, and applicable workers’ compensation rating rules.
For example, a contractor primarily managing lower-risk interior finishing work may have a different premium profile from a business whose employees regularly perform roofing, structural construction, or work at significant heights. Employee duties and accurate classification are therefore important when an insurer calculates premiums.
Payroll is another major consideration because premiums are commonly calculated using payroll amounts and applicable classification rates, with other adjustments potentially affecting the final cost. Businesses with frequent or severe claims may also experience higher costs over time.
General contractors can improve their insurance position by maintaining accurate payroll records, reporting employee duties honestly, implementing workplace safety procedures, and addressing hazards before accidents occur. Comparing suitable insurance proposals can also help identify coverage that fits the business without sacrificing essential protection.
Recent News