How Much Does Workers’ Compensation Insurance Cost for California Construction Companies?
See How We're Different
or call us: 866-226-4436
How Much Does Workers’ Compensation Insurance Cost for California Construction Companies?
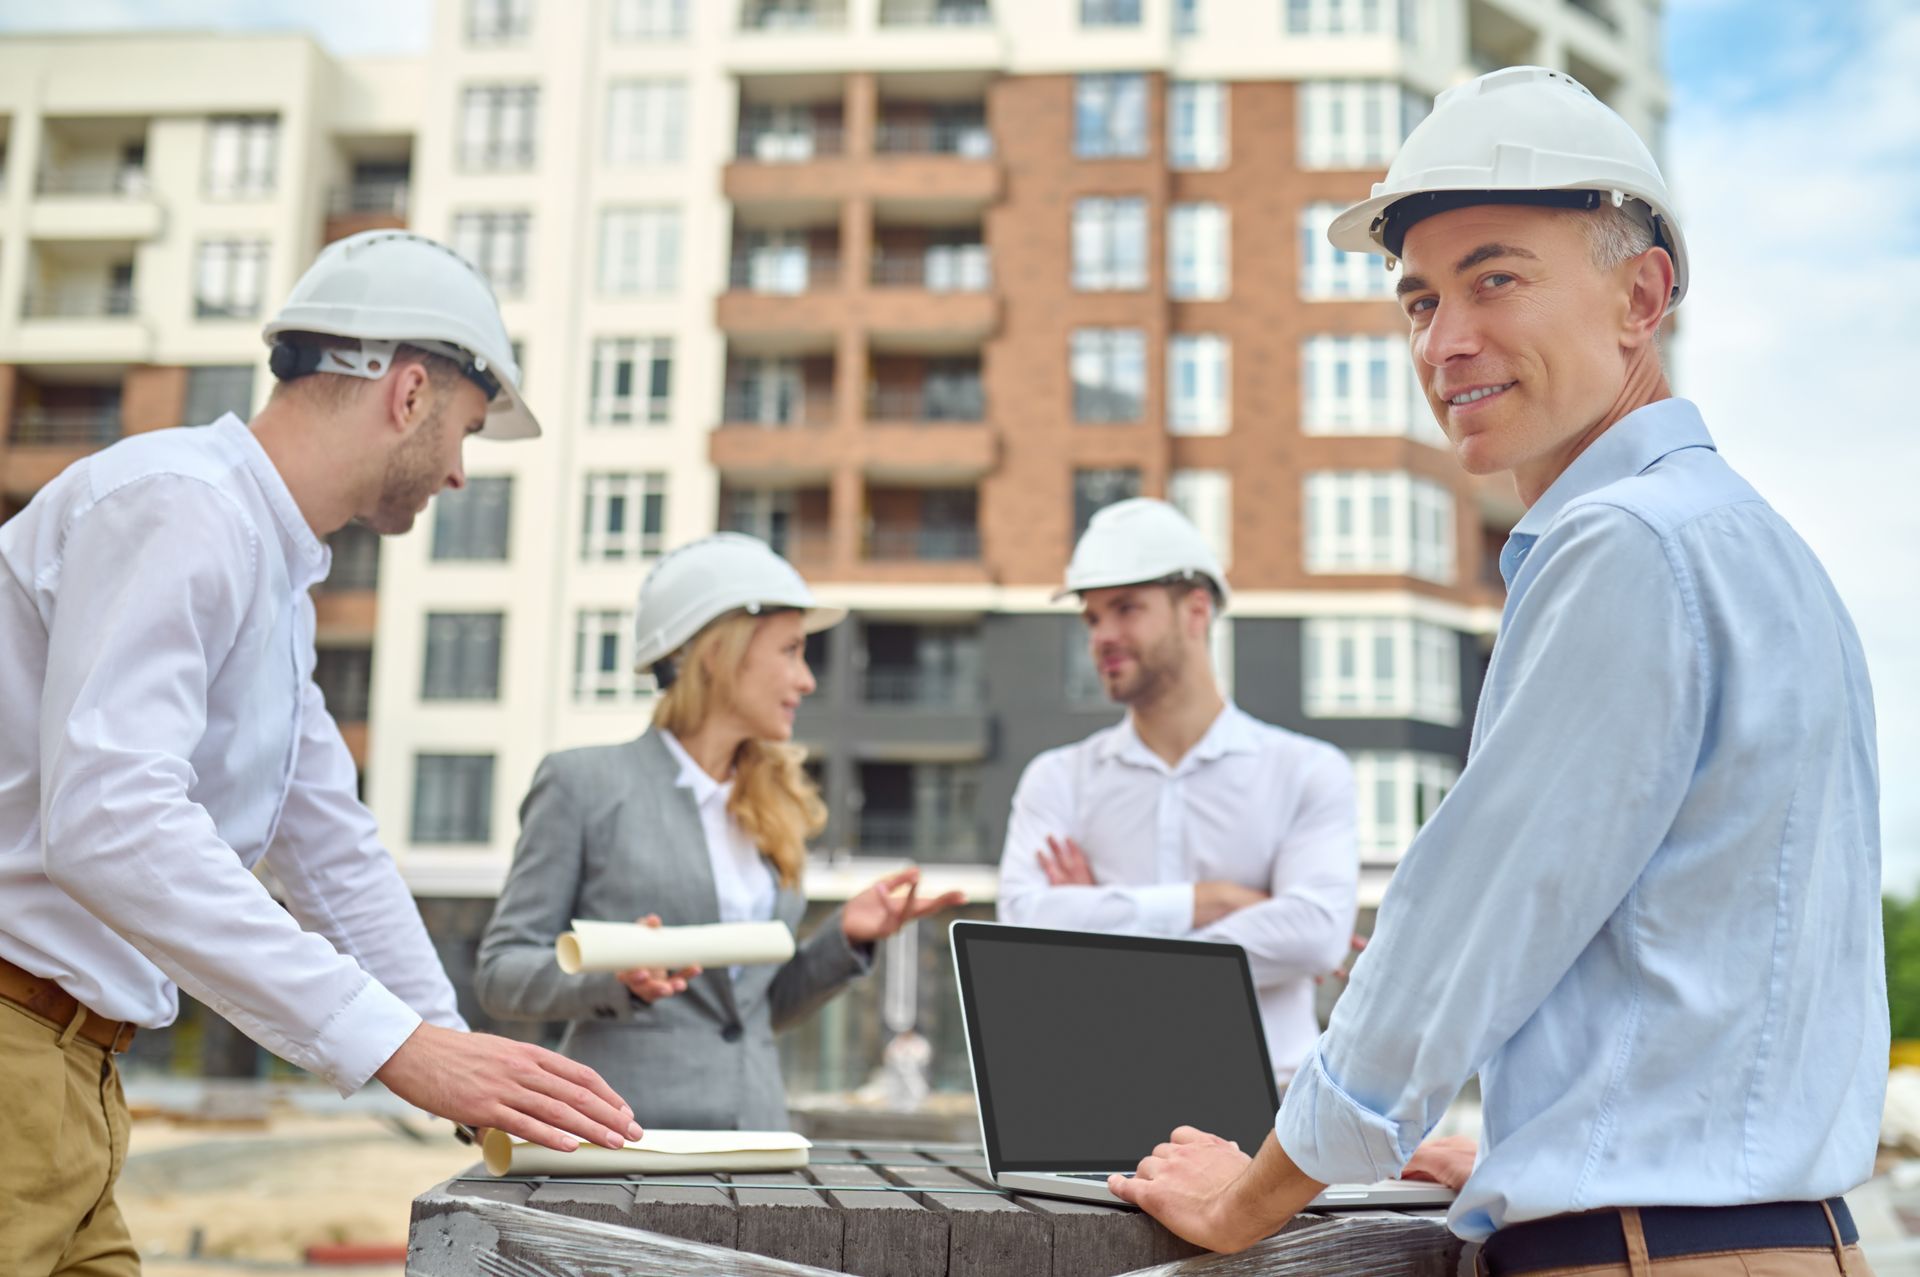
Workers’ compensation insurance is one of the most important expenses for construction companies operating in California. Whether a business specializes in residential remodeling, commercial construction, roofing, electrical work, plumbing, or general contracting, protecting employees against work-related injuries is essential. Construction projects often involve heavy machinery, elevated work areas, hazardous materials, and physically demanding tasks, which can increase the likelihood of workplace accidents.
For California construction companies, the cost of workers’ compensation insurance depends on several factors, including the type of construction work performed, the number of employees, total payroll, claims history, and the company’s workplace safety practices. Some businesses may pay relatively modest premiums, while contractors with high-risk operations and large workforces may face significantly higher expenses.
Understanding these cost factors can help construction business owners prepare accurate budgets, compare insurance options, and identify opportunities to reduce premiums without compromising employee protection.
Average Cost of Workers’ Compensation Insurance for California Construction Companies
There is no single price for workers’ compensation insurance in California because every construction business has a different risk profile. A small contractor employing a few workers may have substantially different insurance expenses from a large construction company managing multiple job sites and dozens of employees.
Insurance premiums are commonly calculated using payroll, classification rates, and an experience modification factor when applicable. Classification rates reflect the risks associated with particular job duties. For example, roofing and structural construction generally involve different levels of exposure than certain administrative or office-based activities.
A company’s annual premium can range from several thousand dollars to tens of thousands of dollars or more, depending on its workforce and operations. Businesses with substantial payrolls or particularly hazardous activities may pay considerably more. Therefore, construction owners should treat general estimates as budgeting guidance rather than guaranteed quotes.
The most reliable way to determine the actual cost is to request a customized quotation based on the company’s payroll records, employee classifications, claims history, and scope of work.
Factors That Influence Insurance Costs
Type of Construction Work
The nature of a construction company’s operations is one of the biggest influences on workers’ compensation premiums. Insurance providers evaluate the likelihood and potential severity of injuries associated with different occupations.
Roofing contractors may face increased exposure to falls, while concrete workers frequently handle heavy materials and operate specialized equipment. Electrical contractors may encounter electrical hazards, and excavation businesses must manage risks involving trenches, machinery, and unstable ground.
Because these occupations present different workplace hazards, they may be assigned different workers’ compensation classification rates. Companies that perform several types of construction work should ensure that employees are classified according to their actual duties and applicable insurance rules.
Total Employee Payroll
Payroll is another major component of workers’ compensation pricing. Premium calculations generally consider the amount of covered payroll assigned to each employee classification. As payroll increases, the potential premium usually increases as well, assuming other rating factors remain unchanged.
For example, a contractor with ten full-time employees will generally have a different insurance cost from a business with thirty employees earning comparable wages. Overtime treatment, employee classifications, and other applicable rating rules can also affect the final calculation.
Construction companies should maintain accurate payroll records and update their insurer when staffing levels or business operations change. Correct reporting helps prevent unexpected adjustments during a premium audit.
Claims History and Experience Modification
An insurer may also consider a company’s previous workers’ compensation claims. Businesses with frequent or expensive claims can face higher premiums than similar companies with stronger loss records.
For eligible employers, an experience modification factor can adjust the premium to reflect historical losses compared with expected losses for comparable businesses. A more favorable factor may help lower costs, while an unfavorable factor can increase them.
Although not every small business receives an experience modification rating, maintaining a strong claims history remains valuable for construction companies of different sizes.
Workplace Safety Procedures
Effective safety management can help reduce injuries, limit lost workdays, and support better long-term insurance results. Construction businesses that provide appropriate training, maintain equipment, enforce protective measures, and investigate workplace incidents may be better positioned to control claims-related expenses.
Safety improvements do not guarantee an immediate premium reduction, because insurance pricing follows applicable rating rules and historical experience. However, reducing preventable accidents can help protect employees while supporting more predictable insurance costs over time.
Recent News