Workers’ Compensation Insurance in California: What Bar and Winery Owners Need to Know
See How We're Different
or call us: 866-226-4436
Workers’ Compensation Insurance in California: What Bar and Winery Owners Need to Know
Running a bar or winery in California involves more than serving drinks, creating memorable customer experiences, and managing daily operations. Business owners must also protect their employees, comply with state employment laws, and prepare for unexpected workplace injuries. One of the most important protections is workers’ compensation insurance, which helps cover eligible medical expenses and lost wages when employees suffer work-related injuries or illnesses.
For bar and winery owners, workplace risks can range from slips and falls to repetitive-motion injuries, burns, lifting accidents, and equipment-related incidents. Understanding California’s workers’ compensation requirements can help business owners avoid costly penalties, support injured employees, and maintain a safer workplace.
Understanding Workers’ Compensation Insurance in California
Workers’ compensation insurance is designed to provide benefits to employees who experience injuries or illnesses arising out of and occurring in the course of their employment. Depending on the circumstances, benefits may include medical treatment, temporary disability payments, permanent disability benefits, supplemental job displacement benefits, and death benefits for eligible dependents.
In California, employers generally must carry workers’ compensation insurance even if they have only one employee. This requirement can apply to full-time staff, part-time workers, and seasonal employees. Bar and winery owners should not assume that a small workforce, limited operating hours, or seasonal business activity automatically exempts them from coverage requirements.
Workers’ compensation generally operates on a no-fault basis. This means an eligible employee may receive benefits without proving that the employer was negligent. In return, the system usually limits an employee’s ability to sue the employer for ordinary workplace injuries, subject to important exceptions.
Why Bars and Wineries Face Unique Workplace Risks
Bars and wineries have different operating environments, but both involve workplace hazards that can lead to employee injuries. Understanding these risks is essential when choosing insurance coverage and developing effective safety procedures.
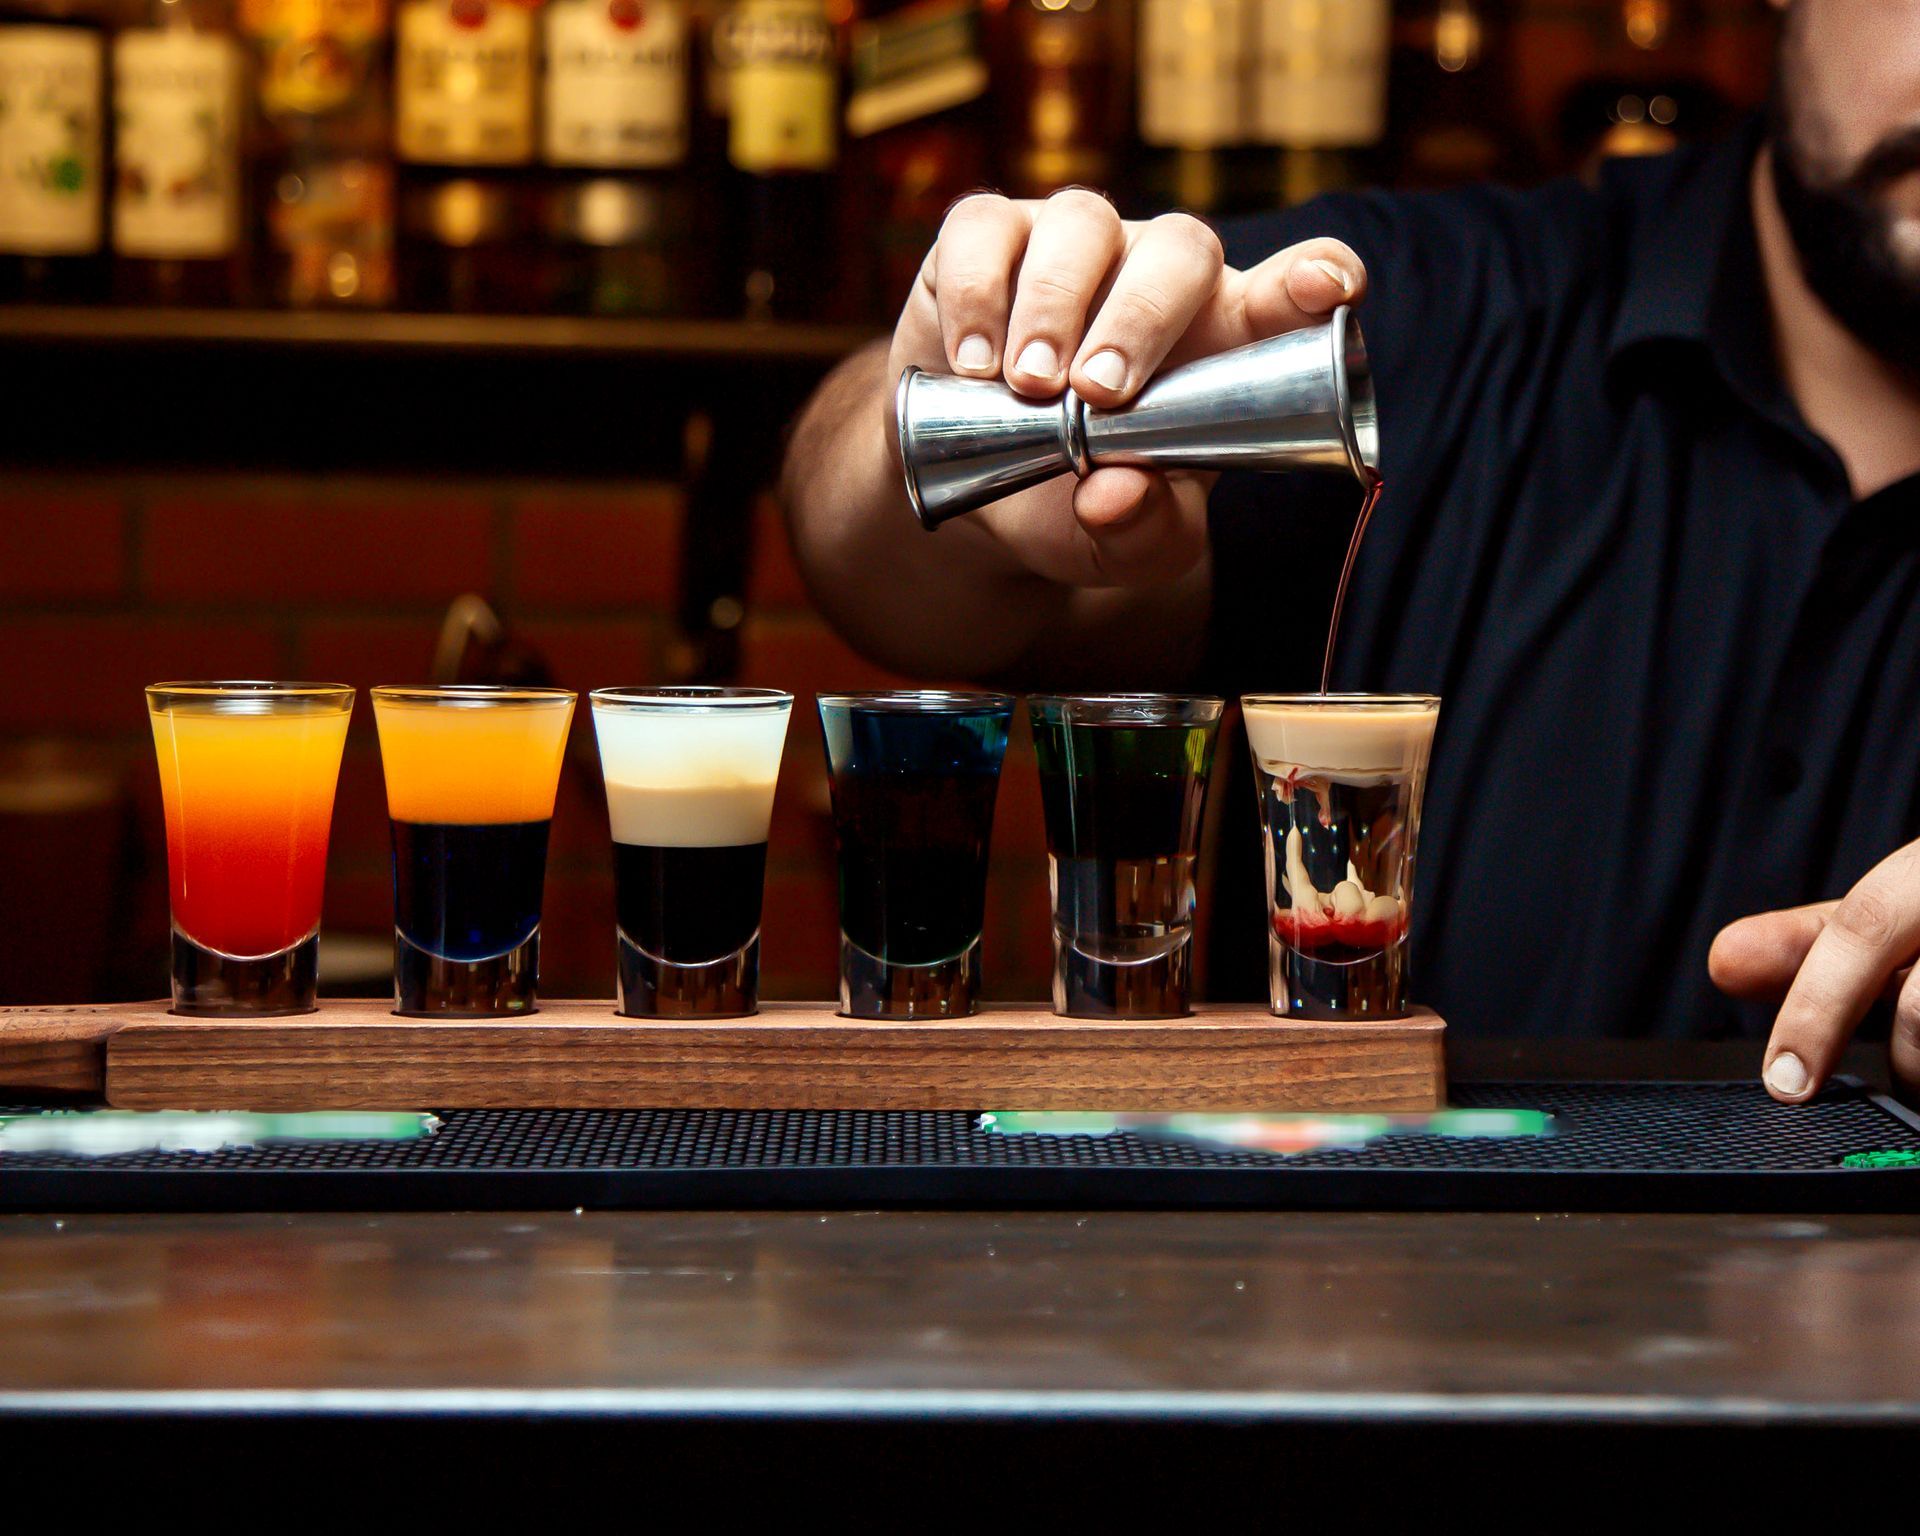
In bars, employees regularly work around wet floors, broken glass, crowded service areas, heavy kegs, sharp tools, and hot equipment. Bartenders may experience wrist, shoulder, or back strain from repetitive movements and prolonged standing. Servers can slip while carrying drinks, while kitchen employees may suffer burns or cuts during food preparation. Late-night operations and busy events can also increase fatigue and the risk of accidents.
Wineries face additional challenges because their operations may involve agricultural work, production equipment, storage tanks, forklifts, bottling machinery, and heavy containers. Employees may lift wine cases, work on uneven outdoor surfaces, or perform physically demanding tasks during harvest season. Cleaning chemicals and confined production spaces can introduce further hazards if appropriate safety procedures are not followed.
Tasting rooms and winery restaurants may combine hospitality risks with production-related hazards. Owners should evaluate each part of their business rather than assuming that one general safety policy will address every potential danger.
California’s Legal Requirements for Business Owners
California employers generally must secure workers’ compensation coverage as soon as they employ workers, unless a specific legal exception applies. Businesses can typically obtain coverage through a licensed insurance company or, if eligible and approved, through California’s self-insurance program.
Failing to maintain required insurance can have serious consequences. An uninsured employer may face substantial financial penalties, enforcement action, and liability for an employee’s work-related medical expenses and other benefits. Authorities may also issue a stop order preventing an uninsured business from using employee labor until coverage requirements are satisfied.
Bar and winery owners should confirm that their policy accurately identifies the legal business entity, covered locations, and relevant operations. If a business expands into catering, live entertainment, winery tours, outdoor events, or additional production activities, the owner should notify the insurance carrier. Accurate information helps reduce the risk of coverage disputes and unexpected premium adjustments.
Owners should also understand that workers’ compensation insurance is separate from general liability insurance. General liability typically addresses certain third-party claims, while workers’ compensation focuses on eligible employee injuries and illnesses. One policy should not be treated as a substitute for the other.
Recent News